UK House Price Index August 2026: what London buyers, owners and executors need to know
London prices fell 2.2% in the year to August 2026 while the UK rose 0.9%. What it means for buyers, landlords and probate, CGT and divorce valuations.
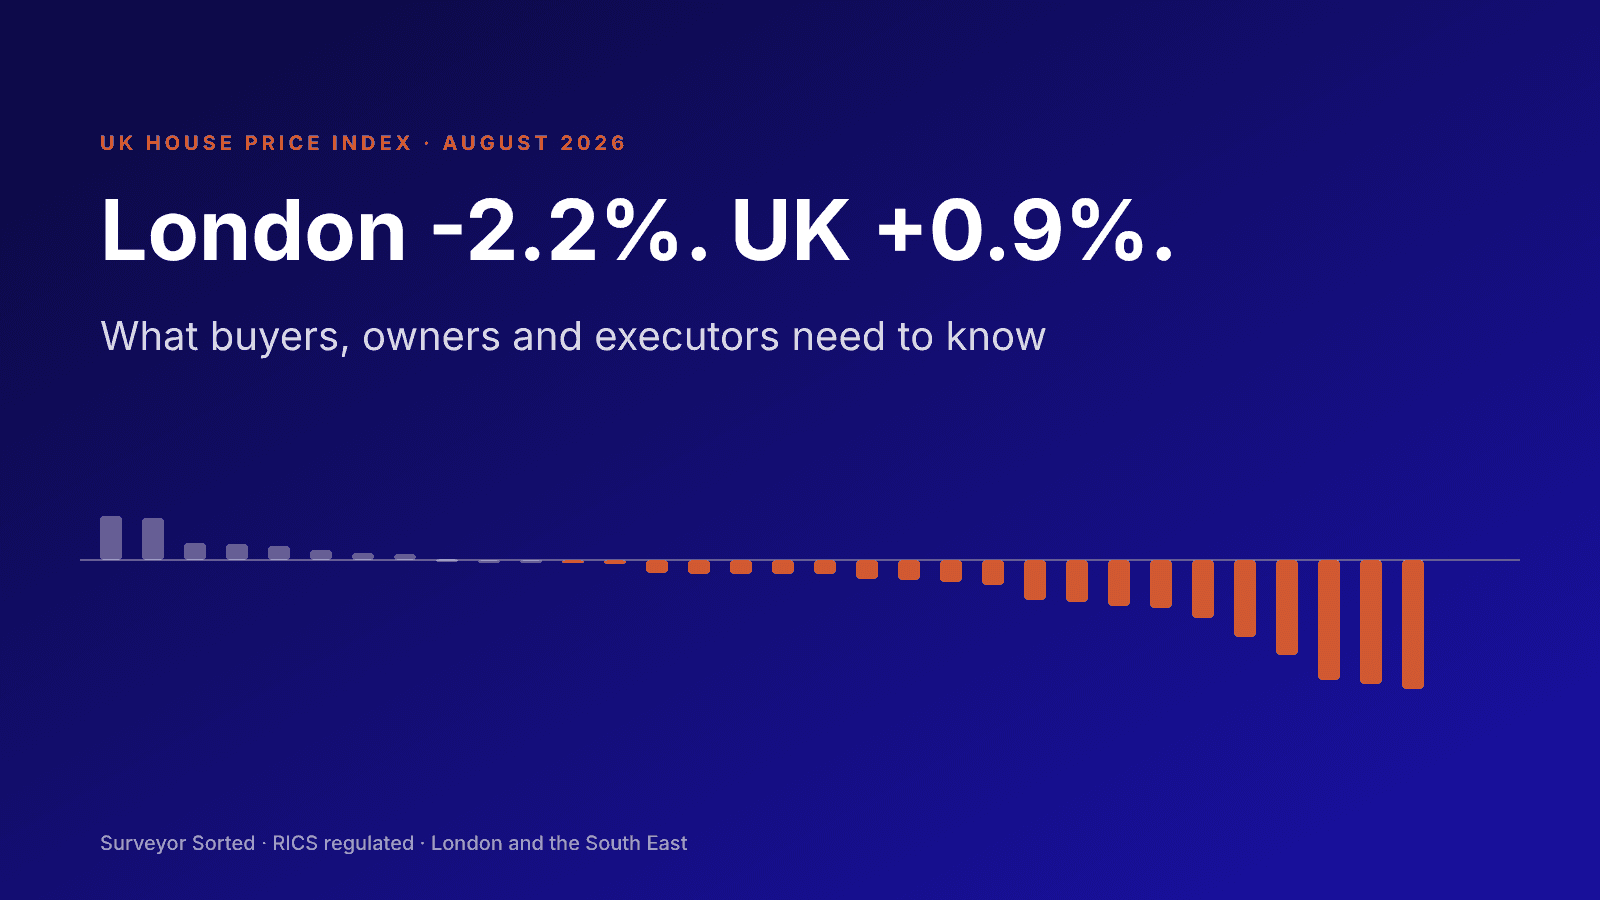
The UK House Price Index for August 2026 landed today with the first sign that London's slide is slowing. Across the UK, prices rose 0.9% on the year to £273,037, the weakest annual growth since March. In London they fell 2.2% to £554,430, a shallower annual fall than the revised 3.2% to July, and prices rose 0.7% in the month itself. Even so, 21 of the 32 boroughs were lower than a year earlier. Underneath the average the story has not changed: London flats are down 5.0% while detached and semi-detached houses are up 1.8%, and the centre of the capital is still correcting while the outer boroughs hold or gain.
Here is what that means if you are buying a home in London, if you own or let property, or if you need a valuation for probate, capital gains tax or a divorce.

The London picture, borough by borough
The average hides a 19-point spread between the top and bottom of the table. Westminster fell 14.3% (on a small and volatile sample, so treat the exact figure with care), Kensington and Chelsea 13.8%, Tower Hamlets 13.3%, Camden 10.6% and Islington 8.6%. Lambeth, Wandsworth, Hammersmith and Fulham, Newham and Barnet were all down 4% to 7%. Every one of those boroughs is a market where flats make up most of the sales.
At the other end, Kingston upon Thames rose 4.9%, Barking and Dagenham 4.7%, Bexley 1.9%, Ealing 1.8% and Sutton 1.5%, with Havering, Enfield and Waltham Forest just above zero and Merton, Hillingdon and Richmond flat. Those are terraced and semi-detached markets where family buyers priced out of Zone 2 are still competing. One caution: borough figures are provisional and get revised, so a borough that read up 1% in July can read down 1% in August once late registrations land, as Haringey and Lewisham did this month.

For homebuyers: flats are a negotiation, houses are a race
The most useful single fact in this release is the gap between property types. Nationally, semi-detached houses rose 2.1% and terraced houses 1.8% over the year while flats fell 1.6%. In London the gap is far wider: flats fell 5.0% while detached and semi-detached houses rose 1.8% and terraced houses were flat. Inside individual boroughs the same pattern repeats. Kingston terraces rose 6.0% while its flats managed 2.5%; Barking and Dagenham terraces rose 5.6% against 2.3% for flats; Hackney terraces rose 1.0% while its flats fell 2.3%; Haringey and Lewisham terraces were flat while their flats fell about 3%. Even in Wandsworth, where everything fell, flats dropped 6.5% against 3.1% for terraced houses, and in Hammersmith and Fulham flats fell 6.4% against 2.2%.

What to do with that:
- Buying a flat, especially in Zone 1 or 2: you have more choice and more leverage than at any point since 2020, and the month-on-month rise in August is a reminder that it will not last forever. Asking prices are lagging the index, and a meaningful share of listings is being withdrawn unsold. A Level 2 or Level 3 survey that prices the defects gives you a written basis to negotiate from rather than a hunch. On leasehold flats, lease length and service charge now move value as much as condition does; get both checked before you commit.
- Buying a terraced or semi-detached house in outer London: competition has not gone away. A well-priced house in Kingston, Barking, Bexleyheath, Ealing or Sutton still attracts several buyers. Do not skip the survey to win the race; a Level 3 on a Victorian or interwar house routinely finds roof, damp and movement issues worth several thousand pounds, and the report is the only leverage you will have after your offer is accepted.
- Relying on the mortgage valuation: it protects the lender, not you. In a soft market it can also come in under the agreed price. An independent RICS valuation at the outset tells you where you actually stand.
For owners, landlords and commercial occupiers
The UK HPI measures residential sales only, so it does not price shops, offices or industrial units. Three residential trends still land on commercial and investor clients:
- Rents are firm while values are soft. London private rents rose 3.5% in the year to September 2026 even as prices fell, so yields on flats have improved for anyone buying now, and landlords selling are competing with a lot of similar stock. A Red Book valuation before you list is cheaper than an overpriced listing that sits for four months.
- Lease extension premiums move with flat values. The premium a leaseholder pays is built on the flat's value, so a fall in the local flat market lowers the premium. If you have been waiting to extend a short lease in Westminster, Kensington, Camden or Tower Hamlets, the arithmetic has moved in your favour. Our lease extension calculator gives an indicative figure.
- Mixed-use and conversion schemes: residential values in central boroughs are the exit price for any office-to-residential or upper-floor conversion. Development appraisals written on 2024 or early 2025 figures need re-running.
For probate, capital gains tax and divorce clients: the date is everything
A falling market changes the value of a property, but it does not change the date the law fixes for valuing it. That distinction decides the tax.
- Probate and inheritance tax. The estate is valued at the open market value on the date of death. If a relative died in early 2025 and the Kensington flat is now worth 15% less, the IHT is still calculated on the 2025 value. There is relief available where a property is sold within four years of death for less than the probate value, but it has to be claimed, and it needs a properly evidenced figure at both dates. A probate valuation to RICS Red Book standard at the date of death, using comparable sales from that period rather than today's asking prices, is what HMRC's Valuation Office expects to see.
- Capital gains tax. The gain is measured from the acquisition cost (or a rebased value, such as April 2015 for non-UK residents) to the disposal value. In a falling market some owners who expected a gain will find a loss, which can be carried forward against future gains, but only if the disposal value is properly evidenced. HMRC compares declared values against the UK HPI trend for the area, so a figure that sits well below the index invites a challenge.
- Divorce and matrimonial settlements. The family home is usually valued at the date of the hearing or agreement. With prices moving 5% to 15% a year in some boroughs, a valuation that is six months old can be materially wrong, and both sides are entitled to a current figure. A single joint expert valuation from a RICS Registered Valuer avoids two competing estate agent opinions.
- Help to Buy redemptions. The government's equity share is repaid as a percentage of the current value, so a lower valuation means a lower repayment. Homes England requires a RICS valuation for exactly this reason.

What we are watching next
The September 2026 index is published on 18 November 2026 and the market data on our area guides is refreshed against each quarterly release. The two things we expect to keep moving are the house-to-flat gap and the spread between central and outer boroughs. The London average is now £15,000 below its July 2025 peak and £8,000 above the March 2026 low, so the next two releases will show whether August's monthly rise was the turn or a pause.
If any of the situations above is yours, a RICS Registered Valuer can give you a figure at the right date with the evidence attached. Surveyor Sorted is a RICS regulated firm covering London and the South East.
This article is general information based on published HM Land Registry and ONS data. It is not tax or legal advice; for the tax treatment of a specific estate or disposal, speak to your solicitor or accountant.
Quick answers
Frequently asked questions
- Are London house prices falling in 2026?
- Yes, but the pace of the fall eased in August. The UK House Price Index for August 2026, published 21 October, puts the average London price at £554,430, down 2.2% on a year earlier after a revised 3.2% fall to July, with 21 of the 32 boroughs lower. The UK as a whole rose 0.9% to £273,037. The fall is concentrated in flats, down 5.0% across London, and in the central boroughs; a handful of outer boroughs are still rising.
- Which London boroughs fell the most in the year to August 2026?
- Westminster (down 14.3% on a small, volatile sample), Kensington and Chelsea (down 13.8%), Tower Hamlets (down 13.3%), Camden (down 10.6%), Islington (down 8.6%), Lambeth (down 6.5%), Wandsworth (down 5.3%) and Hammersmith and Fulham (down 5.1%). All are markets where flats dominate the sales.
- Which London boroughs are still rising?
- Kingston upon Thames (up 4.9%), Barking and Dagenham (up 4.7%), Bexley (up 1.9%), Ealing (up 1.8%), Sutton (up 1.5%), Havering (up 1.1%), Enfield (up 0.8%) and Waltham Forest (up 0.7%), with Merton, Hillingdon and Richmond flat. These are markets dominated by terraced and semi-detached houses.
- Are flats or houses falling faster?
- Flats, by a wide margin. Across the UK, flats and maisonettes fell 1.6% in the year to August 2026 while semi-detached houses rose 2.1% and terraced houses 1.8%. In London, flats fell 5.0% while detached and semi-detached houses rose 1.8% and terraced houses were flat at 0.1%. In Westminster flats fell 15.1%; in Kingston upon Thames terraced houses rose 6.0%.
- Does the UK House Price Index cover commercial property?
- No. The UK HPI measures residential sales registered with HM Land Registry only. Commercial property is valued on rental evidence and yields, but residential trends still matter for mixed-use buildings, residential conversions, lease extension premiums and development appraisals.
- How does a falling market affect a probate or capital gains tax valuation?
- The valuation date is fixed by the event, not by today. A probate (inheritance tax) valuation is the open market value at the date of death; a capital gains tax valuation is at the date of disposal or, for older assets, at an earlier base date such as April 2015 for non-residents. When values are falling, the date and the evidence behind it decide the tax, so a RICS Red Book valuation at the correct date carries far more weight with HMRC than an estate agent's appraisal.
- Where do the figures come from?
- HM Land Registry and the Office for National Statistics publish the UK House Price Index monthly, about six to seven weeks after the reference month. The August 2026 figures were published on 21 October 2026 and are provisional; local figures are revised in later releases, and the September 2026 data follows on 18 November 2026.
Areas covered
Free · No obligation
Get a quote for your property
RICS regulated surveyors across London and the South-East. For most surveys the fee shows on screen before you share any contact details.